Instant asset write-off

The instant asset write off allows eligible Australian businesses to immediately claim deductions for certain costs relating to depreciating assets.

Depreciating assets are a type of asset that has a limited effective life and can reasonably be expected to decline in value over the time that it is being used. Common business examples include things like computers, electric tools, and cars.

The Federal Budget 2020-21 introduced temporary measures due to COVID-19, updating the instant asset write off that was previously in place.

For assets already used or installed between Marth 12th 2020 until June 30th 2021, and purchased by December 31st 2020, the instant asset write-off threshold amount for each asset is $150,000 (up from $30,000). Eligibility extends to businesses with the accumulated turnover of less than $500,000,000 (up from $50,000,000).

And from 7:30pm on October 6th 2020 until June 30th 2022, this has been updated further to allow for temporary full expensing allowed for certain deductions. This includes the business portion of the cost of new eligible depreciating assets for businesses with an aggregated turnover of under $5 billion for corporate tax entities that satisfy the alternative testing. It also affects the business portion of the cost of eligible second hand assets for businesses with an aggregated turnover of under $50,000,000. And lastly, the balance of a small business pool at the end of each income year in this period for businesses with an aggregated turnover of under $10,000,000.

Your eligibility

Eligibility for the Instant Asset Write Off on an asset depends of these certain things: 
- Your aggregated turnover (the total ordinary income of your business and that for any associated businesses)
- The date on which you purchased the asset
- When the asset was first installed ready for use, or actually used
- The cost of the asset being less than the current or relevant threshold

You are not eligible for the instant asset write off on an asset if your aggregated turnover is more than $500,000,000. And if the temporary full expensing applies to a particular asset, you do not need to apply the instant asset write off.

Thresholds

The thresholds have changed over the years so it is important to reference the most up to date information to see what applies and does not apply.

Instant asset write off thresholds for small businesses that apply the simplified depreciation rules are as follows: (*sourced from www.ato.gov.au):
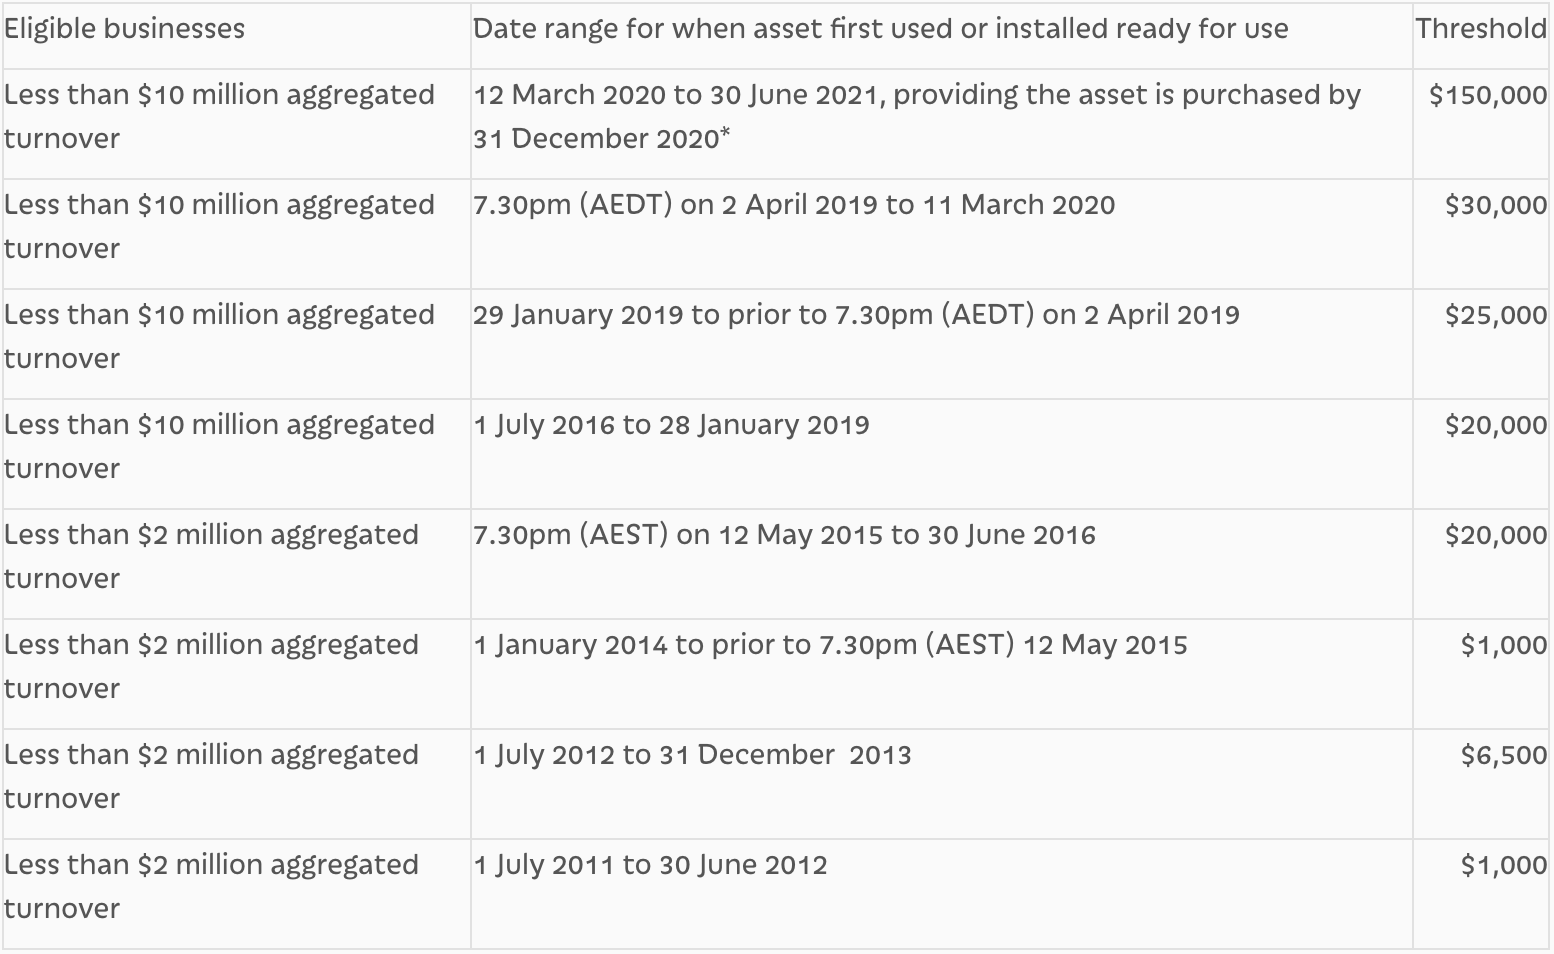
* You must have purchased the asset on or after 7.30pm (AEST) on 12 May 2015.

There are also several exclusions and limitations to the instant asset write off. These include, but are not limited to, car limits applied to the cost of passenger vehicles and a small list of other assets including things that will be expected to be leased out for more than 50% of the time and capital works.

What next?

Before deciding to make any large purchases for your small business, chatting to your tax agent or accountant will help a lot. Especially when it comes to assessing how an asset will benefit your business and how the purchase could impact your cash flow or finances in the short term.

If you do decide to take advantage of the instant asset write off, you should make this decision based on the needs of your business and that align with your business plans and goals.

Need help with your accounting?

Find Out What We Do
September 14, 2026
In your 50s and thinking about retirement? Discover 10 practical strategies to boost your super and get your retirement savings on track.
September 14, 2026
Buying your first home? From deposit schemes to stamp duty concessions, here are 5 government schemes that could help you get into the market sooner.
September 14, 2026
A new way to claim work-related expenses is coming for the 2027 tax return — but there is an important catch. From 1 July 2026, eligible taxpayers can claim a standard deduction of up to $1,000 for certain work-related expenses, without having to substantiate each expense individually. Sounds simple enough. But before you assume you can claim $1,000 on top of everything else, there are a few things you need to know. The $1,000 Is the Maximum The new standard deduction is capped at $1,000. It is designed to cover certain common work-related expenses, such as work-related phone and internet, home office expenses, stationery and some travel expenses. You can't claim the $1,000 and then claim those same expenses again separately. If you have actual work-related expenses of more than $1,000, you can continue to claim your actual expenses under the existing rules, provided you meet the requirements and have the records to support them. Do I Still Need to Keep My Receipts? Yes: and this is where it is worth being organised. If you use the standard deduction, you don't need to substantiate the individual expenses covered by it. But if you think your actual work-related expenses could be more than $1,000, keeping your receipts and records throughout the year will allow you to claim your actual expenses instead. There are also some deductions that aren't covered by the standard deduction and can still be claimed separately if you are eligible. It's for Your 2027 Tax Return The new deduction applies from the 2026–27 financial year, so you won't use it for the tax return you are preparing now. It will first apply to your 2027 tax return, lodged from July 2027. Is the $1,000 a $1,000 Tax Refund? No. The $1,000 is a deduction from your taxable income. It doesn't mean you'll receive an extra $1,000 back from the ATO. The value of the deduction will depend on your individual tax circumstances. What Should You Do Now? The best thing you can do is keep track of your work-related expenses throughout the 2026–27 financial year. When it comes time to prepare your 2027 tax return, we can look at your circumstances and determine whether the standard deduction or claiming your actual expenses is likely to give you the better outcome.  At Ascent Accountants, we can help you make sense of the new rules and make sure you're claiming the deductions you're entitled to: without claiming the same expense twice!
By Nigel Parker August 13, 2026
Late paying super under Payday Super? Learn the new deadlines, penalties, and the one step that can reduce your Administration Uplift charge.
By Nigel Parker August 13, 2026
Received a business name or company renewal notice that looks official? Learn how to spot a fake ASIC notice before you pay.
By Nigel Parker August 13, 2026
Negative gearing is changing from 1 July 2027. Find out what it means for established properties, new builds, and your next investment.
More Posts