November 11, 2026
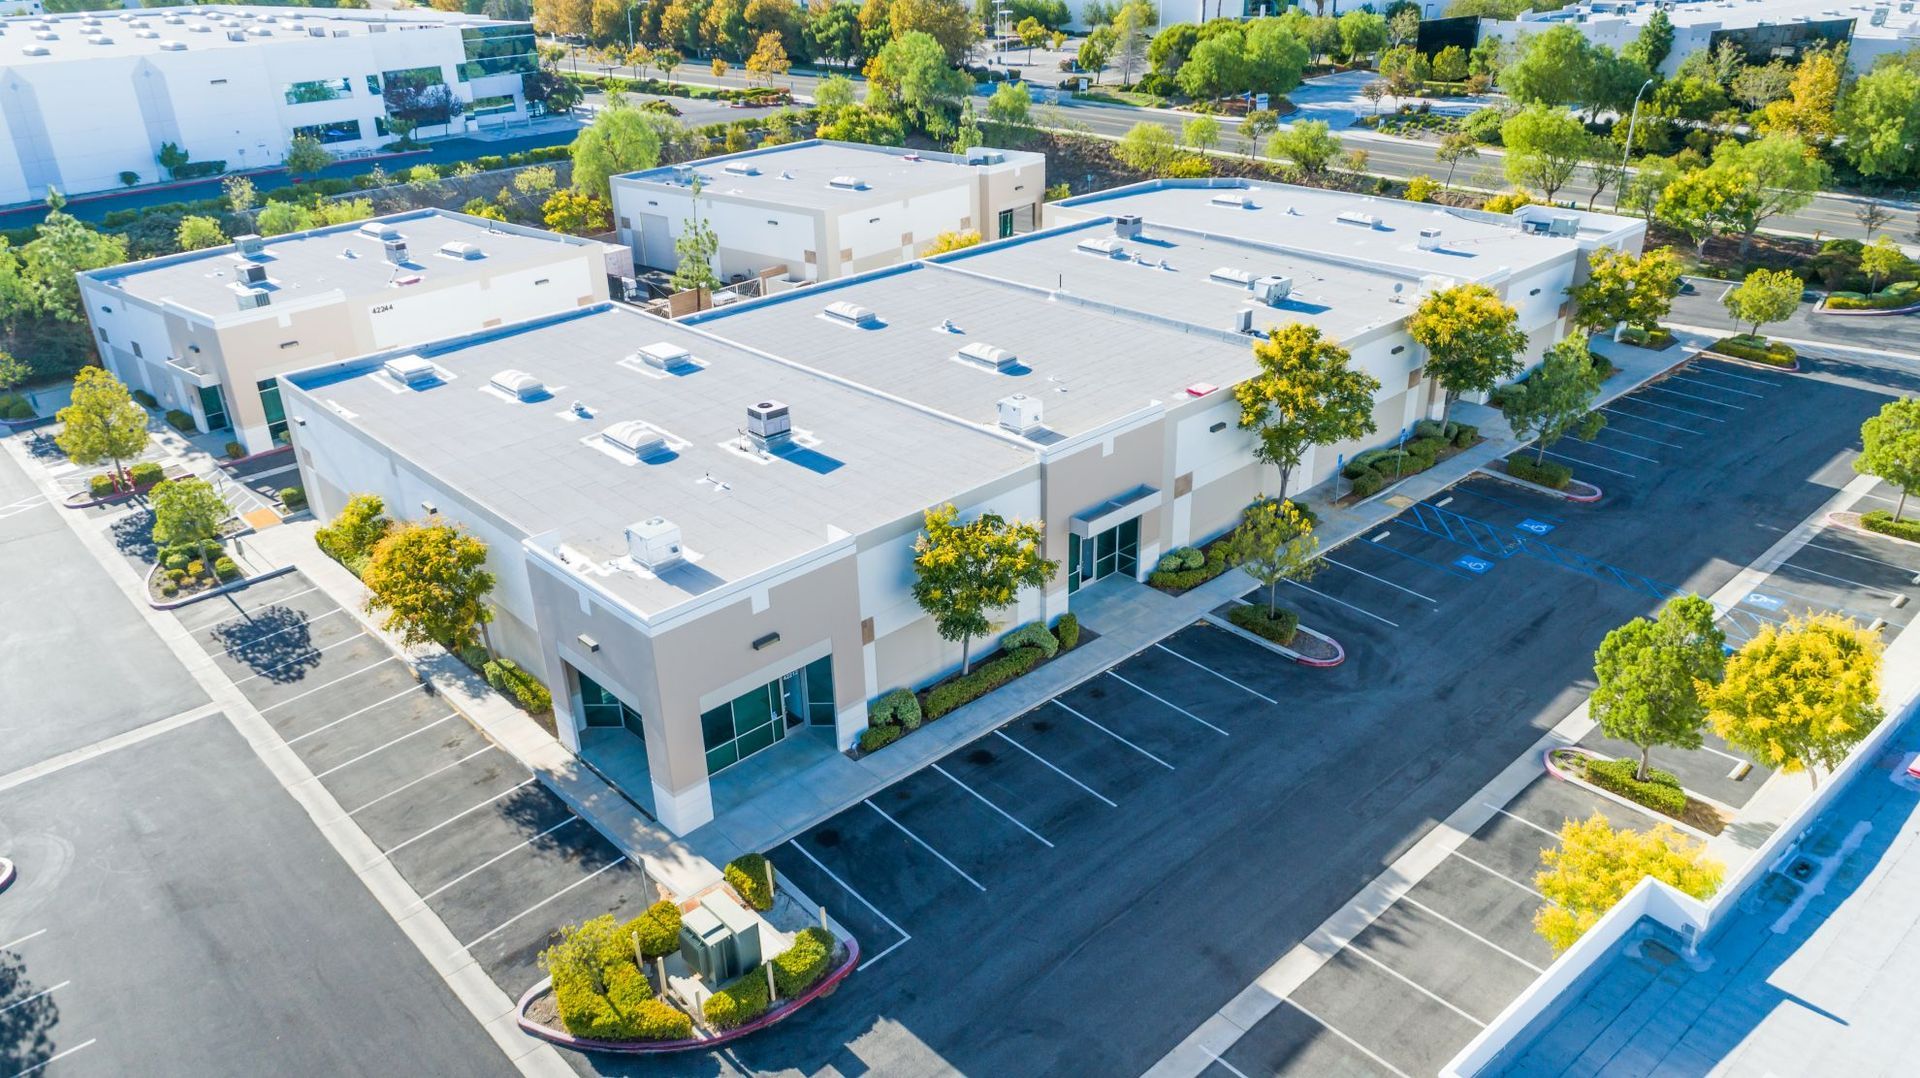
Commercial property can be an attractive investment for business owners and investors looking to diversify their portfolios, generate rental income and build long-term wealth. But commercial property investment works differently from residential property, particularly when it comes to financing, rental returns, tax deductions and the use of a Self-Managed Super Fund (SMSF). With recent changes to SMSF borrowing rules, understanding your options before purchasing is more important than ever. What Makes Commercial Property Different? Commercial property includes offices, warehouses, factories, retail premises and other properties used for business purposes. Compared with residential property, commercial investments can offer several potential advantages. Leases are often longer, providing greater certainty around rental income. Tenants may also be responsible for certain outgoings, such as council rates, insurance and maintenance, depending on the lease agreement. Commercial properties can also offer higher rental yields than residential properties, although returns vary considerably depending on the property, location, tenant and market conditions. However, commercial property is not without risk. Vacancies can last longer, properties can be more difficult to sell and the financial impact of losing a tenant can be significant. Can You Negatively Gear Commercial Property? Yes. Commercial property can still be negatively geared. Negative gearing occurs when the costs of owning and operating an investment property exceed the rental income it generates. For example, if your commercial property generates $60,000 in annual rent but incurs $75,000 in eligible expenses, the property produces a $15,000 loss. Depending on how the property is owned and the applicable tax rules, this loss may be deductible against other assessable income. Eligible expenses may include: Interest on investment borrowings. Property management fees. Council rates and insurance. Repairs and maintenance. Certain other property-related expenses. The tax treatment will depend on the ownership structure and the nature of each expense. Importantly, the recent negative gearing reforms commencing on 12 May 2026 relate to residential property. They do not introduce the same restrictions for commercial property. This means commercial property investors can continue to consider negative gearing under the existing tax rules, subject to the usual requirements. Can Your SMSF Buy Commercial Property? A Self-Managed Super Fund can be used to purchase commercial property, provided the fund complies with superannuation and investment rules. For business owners, one potential strategy is for the SMSF to purchase commercial premises and lease them to the business operating from that property. This can allow the business to pay rent to an entity that forms part of the owner's retirement savings strategy, rather than paying rent to an unrelated landlord. However, the arrangement must meet strict requirements. Where the property qualifies as Business Real Property, an SMSF can generally lease it to a related business, provided the arrangement is conducted on commercial, arm's-length terms. What About Borrowing Through an SMSF? Recent changes to Limited Recourse Borrowing Arrangements (LRBAs) have significantly changed the SMSF property landscape. From 10 August 2026, new SMSF borrowing arrangements could generally no longer be used to acquire ordinary residential investment property. However, SMSFs can still borrow to acquire eligible Business Real Property. This means commercial premises, such as qualifying offices, warehouses and factories, can remain an option for SMSFs using an LRBA. Existing residential borrowing arrangements are generally protected under the transitional rules, and eligible business property borrowing remains available. It is important to understand that not every property described as commercial automatically qualifies as Business Real Property. The property's actual use and the requirements under superannuation law must be considered. What Should You Consider Before Investing? Commercial property can offer attractive opportunities, but there are several important factors to assess before committing. 1. Cash flow Consider the rental income, borrowing costs, property expenses and the potential impact of vacancies. 2. Tenant risk A commercial property may depend heavily on one tenant. If that tenant leaves, finding a replacement can take time. 3. Location and demand The property's location, accessibility, surrounding businesses and demand for that type of premises will influence its investment potential. 4. Liquidity Commercial property can take longer to sell than other investments. This is particularly important for SMSFs, which need sufficient liquidity to meet their obligations. 5. Ownership structure Whether you purchase personally, through a company, trust or SMSF can have significant tax, legal and financial implications. Is Commercial Property Right for You? Commercial property can be a valuable part of a broader investment or retirement strategy, particularly for business owners who may have the opportunity to purchase their own premises. However, the right structure, financing arrangements and tax treatment need to be considered before you buy. At Ascent Accountants, we can help you understand the tax implications of commercial property investment, assess potential ownership structures and consider whether purchasing through an SMSF may be appropriate for your circumstances. Getting the right advice before signing a contract can help you avoid costly mistakes and make a more informed investment decision.